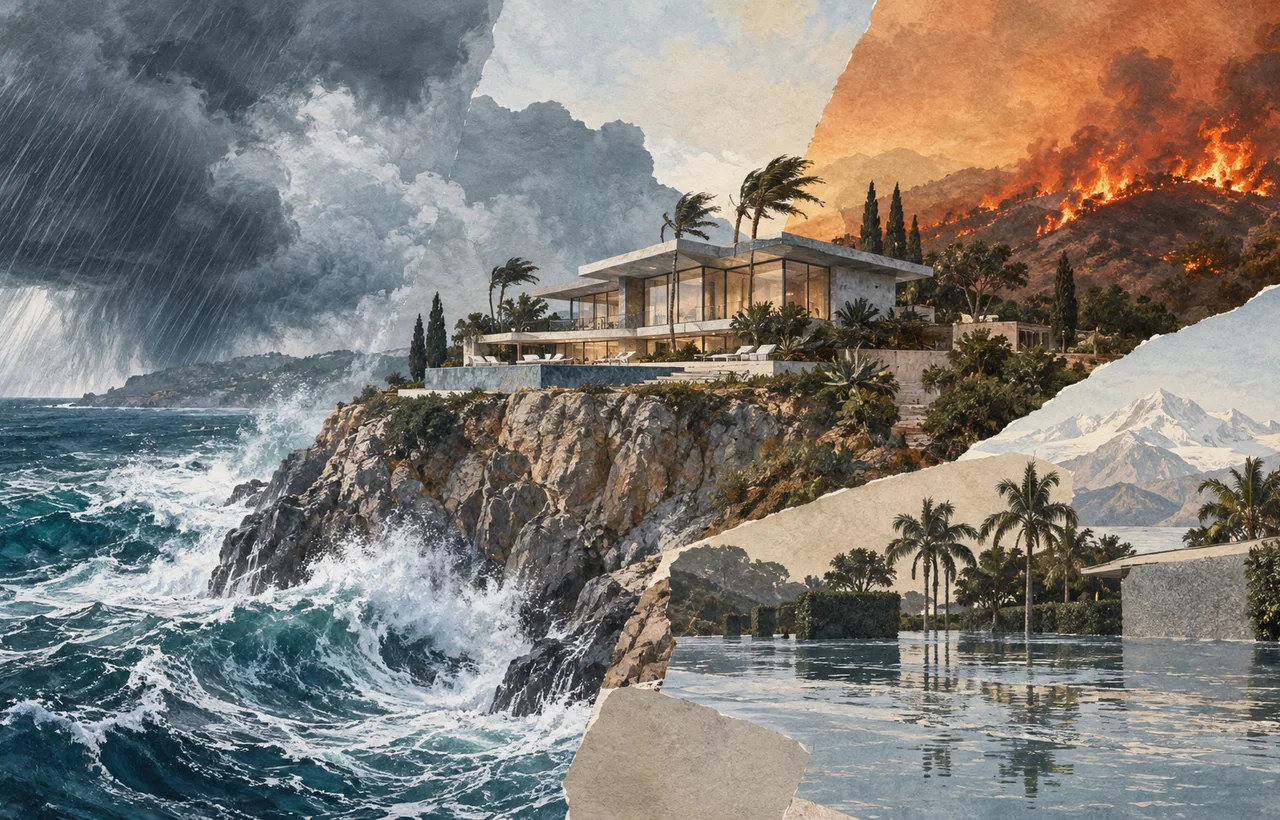
The phrase “climate-proof” is useful marketing and poor risk language. Heat, flood, fire, wind, water scarcity and insurance availability can change a property's value even when the building itself is well engineered.
Start with the hazard, not the amenity list
A defensible assessment looks at present and projected hazards for the exact site. Buyers should compare public flood and fire maps with elevation, drainage, building materials, evacuation routes and the reliability of power and water systems.
Regional averages are not enough. Two homes in the same postcode can have very different exposure because of slope, vegetation, shoreline change or the capacity of local infrastructure.
Insurance is a price signal
Premiums, deductibles, exclusions and insurer withdrawal can reveal risks that a listing does not. A buyer should obtain written insurance indications before closing and test how ownership costs change under less favorable renewal terms.
Resilience features also need scrutiny. Backup power, flood barriers and fire-resistant landscaping only work when maintained, tested and supported by community-scale systems.
A practical due-diligence file
The strongest file includes an independent building assessment, hazard maps, loss history, insurance terms, utility resilience, local adaptation plans and likely capital expenditure. It should distinguish protections that reduce damage from claims that imply risk has disappeared.
A resilience premium can be rational when evidence supports lower disruption and loss. It should never rest on the label “climate-proof” alone.
Original references
Sources & further reading
- SEC investor resources ↗www.investor.gov
- Federal Reserve economic data ↗fred.stlouisfed.org